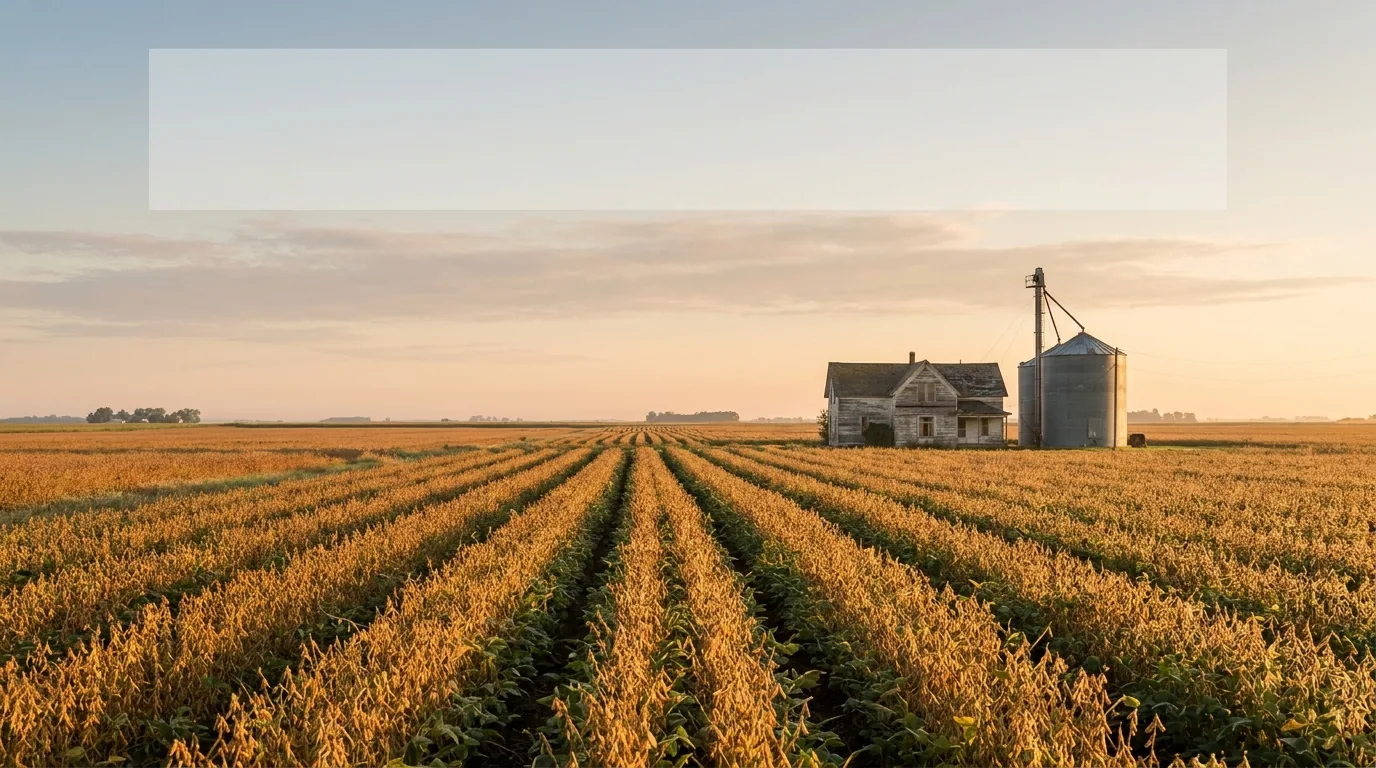
Farmland can provide an alternative to traditional stock and bond investments, but investing in it doesn't necessarily mean buying a farm and working the land yourself. You may gain exposure through publicly traded investments, private pooled vehicles, or direct ownership.
Each route comes with different minimum investments, liquidity, costs, risks, and levels of control. Understanding those differences is essential before deciding whether farmland belongs in your broader investment strategy.
Understand Where Farmland Returns Come From
Farmland can potentially generate returns from more than one source.
If you own land and lease it to a farmer, rent may provide recurring income. The property's value may also appreciate, potentially creating a gain when it's eventually sold. An owner who actively operates a farm could earn additional income from crops, livestock, or other agricultural activities.
None of these returns is guaranteed. Land prices can decline, tenants can leave, agricultural income can fluctuate, and ownership expenses continue even when a property isn't producing income.
Consider Publicly Traded Investments
One of the most accessible ways to gain agricultural or farmland-related exposure is through publicly traded investments.
Some real estate investment trusts own agricultural properties and lease them to farmers. Other investment funds provide broader exposure to agricultural businesses, commodities, or related industries.
These investments can generally be purchased through a brokerage account and traded during market hours.
However, agricultural funds aren't necessarily the same as owning farmland. Some hold shares of companies involved in farming, equipment, chemicals, food production, or other agricultural activities rather than physical land.
Similarly, a publicly traded real estate investment can fluctuate with financial markets in addition to being influenced by the value and performance of its underlying properties.
Private Farmland Investments Work Differently
Private investment platforms and pooled funds can provide another route to farmland exposure.
Depending on the investment, your money may be directed toward a particular farm, orchard, or group of agricultural properties. Some opportunities may also be restricted to investors who satisfy applicable eligibility requirements.
Private investments can have higher minimums and longer holding periods than publicly traded alternatives. Your ability to withdraw or sell may also be limited.
Before investing, understand what property you're investing in, how income is generated, the fees involved, and when you'll realistically be able to access your money again.
Direct Ownership Provides More Control
Buying farmland directly gives you greater control over the property, but it also requires significantly more capital and involvement.
You might purchase existing farmland and find a tenant, buy property from an operator who continues farming it under a lease, or acquire land that needs to be converted for agricultural use.
The last approach can introduce additional risks involving permits, development expenses, water availability, soil suitability, and finding an operator.
Direct ownership also means taking responsibility for property taxes, maintenance, insurance, legal arrangements, and other ongoing expenses.
Evaluate the Property Carefully
Farmland isn't interchangeable simply because two properties contain the same number of acres.
Important considerations can include:
- Soil quality and productivity
- Water and irrigation access
- Drainage
- Location and transportation
- Existing infrastructure
- Environmental conditions
- Local agricultural demand
- Property taxes and maintenance
- Lease terms and tenant quality
Specialized agricultural knowledge can be valuable when evaluating these factors.
Don't Overlook Tenant Risk
If rental income is central to your strategy, the quality of the tenant matters.
Review the prospective operator's experience, financial condition, farming history, and ability to manage the particular type of property.
The lease itself also deserves careful attention. Understand how rent is calculated, who pays particular operating expenses, how long the agreement lasts, and what happens if either party wants to end or renegotiate the arrangement.
A parcel without a reliable tenant may produce little or no rental income while ownership costs continue.
Understand the Liquidity Tradeoff
Physical farmland is considerably less liquid than publicly traded securities.
Selling requires finding a buyer willing to purchase the specific property at an acceptable price. Depending on the location, agricultural market, property condition, and buyer demand, that process can take time.
Private farmland investments may impose their own restrictions, including multiyear holding periods or limited opportunities to sell.
Publicly traded investments generally offer greater liquidity, but their market prices can fluctuate daily.
Be Careful With the Inflation-Hedge Argument
Farmland is sometimes presented as an inflation hedge because land is finite and agricultural production serves continuing demand.
That doesn't mean farmland will automatically increase in value whenever inflation rises.
Property values can be affected by interest rates, agricultural commodity prices, local demand, weather, water availability, development pressure, operating costs, and broader economic conditions.
Treat potential inflation protection as one characteristic to evaluate rather than a guaranteed outcome.
Consider Tax Implications
Tax treatment can vary depending on whether you directly operate the farm, passively lease the property, invest through a fund, or eventually sell the investment.
Active and passive participation can also be treated differently under applicable tax rules.
Because farmland can involve rental income, operating income, capital gains, and property-specific tax considerations, professional tax guidance may be useful when evaluating a substantial investment.
Look Beyond Historical Volatility
Farmland has sometimes displayed lower measured price volatility than stocks, which can make it attractive as a potential portfolio diversifier.
But low reported volatility doesn't necessarily mean low risk.
Farmland isn't continuously traded like publicly listed stocks, so property values aren't repriced every second of the trading day. Investors still face risks involving weather, tenants, water, agricultural markets, financing, property values, and liquidity.
Choose the Route That Fits Your Strategy
Farmland exposure can range from relatively accessible publicly traded investments to private funds and direct property ownership.
Public investments may offer easier entry and greater liquidity but bring stock-market exposure. Private vehicles can provide more direct exposure while introducing eligibility requirements, larger minimums, fees, and potential lockups. Direct ownership provides the greatest control while demanding more capital, expertise, and ongoing management.
Before investing, compare the complete picture: expected income, fees, taxes, liquidity, property-specific risks, holding period, and how farmland would fit alongside the rest of your portfolio. Diversification can help manage concentration risk, but it cannot guarantee against investment losses.