Commission-free stock and ETF trading has made the basic cost of investing similar across many online brokerages. The bigger differences often appear elsewhere: which investments you can buy, what account types are supported, whether managed portfolios are available, and what fees apply to more specialized services.
Understanding these distinctions can help you choose a brokerage around your long-term investing needs rather than focusing only on free trades.
Start With the Available Investments
Not every brokerage gives you access to the same asset classes.
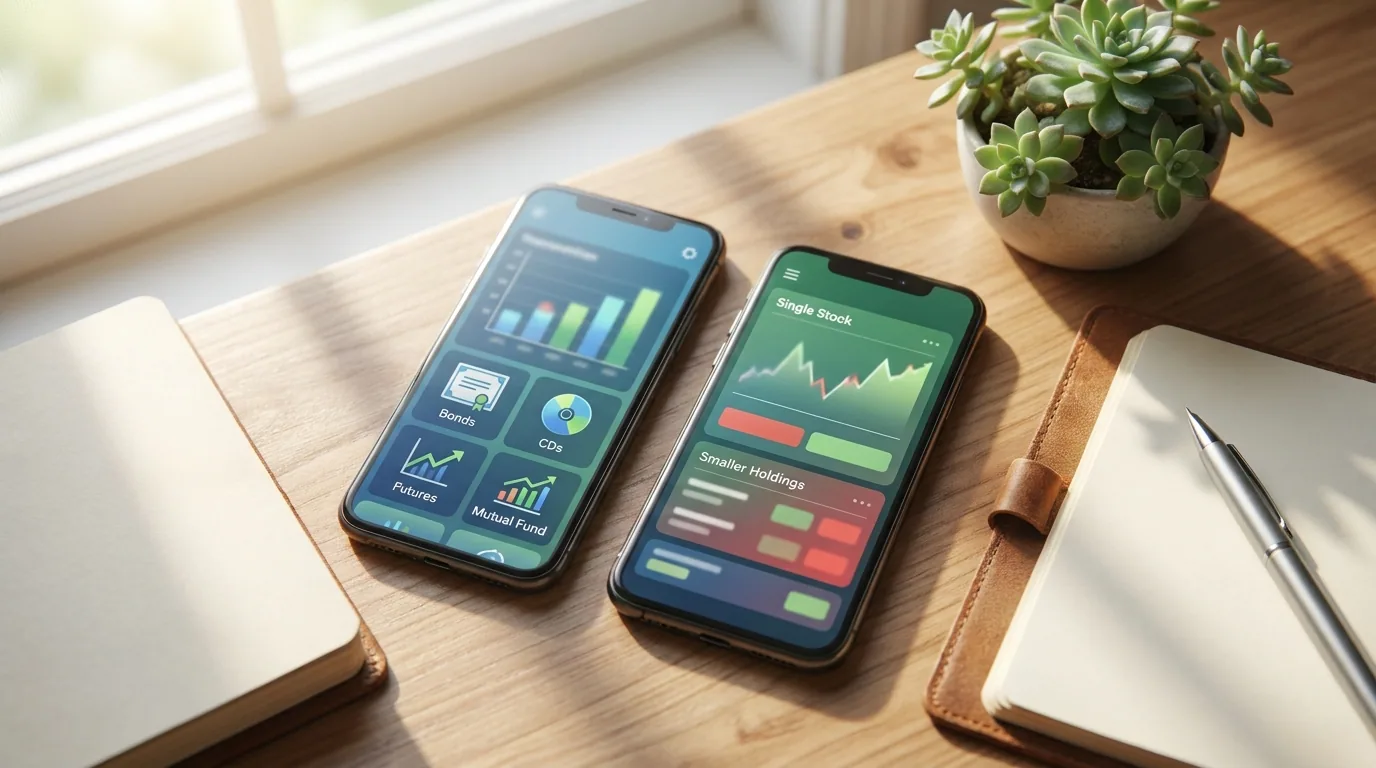
Stocks, ETFs, and options are widely available, but access to mutual funds, individual bonds, certificates of deposit (CDs), futures, cryptocurrency, and other investments varies considerably.
This matters because your available investments determine how you can construct a portfolio.
For example, a platform without individual bonds may still offer bond ETFs. However, owning a bond fund isn't identical to owning individual bonds with specific maturity dates.
Consider what you expect to invest in today as well as what you might want several years from now.
Look Beyond Commission-Free Trading
A brokerage advertising $0 commissions on stock and ETF trades can still have other costs.
Depending on the platform and activity, you might encounter:
- Options contract fees
- Margin interest
- Managed-portfolio fees
- Account transfer charges
- Fund expenses
- Subscription fees
These expenses may matter more than ordinary trading commissions, particularly if you frequently trade options, use margin, or pay for portfolio management.
Review the complete fee schedule rather than assuming "commission-free" means cost-free.
Decide Whether You Want to Manage the Portfolio Yourself
Self-directed and managed investing provide very different experiences.
With a self-directed account, you choose the investments, decide how much to allocate to each one, and determine when to buy or sell.
Some brokerages also offer managed portfolios. These services typically recommend or build an investment portfolio based on your goals, time horizon, and risk tolerance, then handle tasks such as allocation and rebalancing.
Managed investing usually comes with an additional advisory fee.
If you want professional guidance, also determine whether the brokerage provides automated management, access to human advisors, or both.
Compare Retirement Account Options
Traditional and Roth IRAs are common, but retirement offerings can extend well beyond them.
Some brokerages support rollover IRAs, SEP IRAs, SIMPLE IRAs, Solo 401(k)s, custodial retirement accounts, and retirement plans designed for small-business owners.
This may not seem important when you're opening your first taxable account, but your financial situation can change.
If you later become self-employed, start a business, or need to move assets from an employer-sponsored retirement plan, broader account availability can make managing your investments more convenient.
Consider Custodial and Education Accounts
Families may also want to look beyond standard brokerage and retirement accounts.
Some platforms provide custodial accounts that allow adults to invest for minors. Education-oriented accounts may also be available.
If you're planning to invest for a child or future education expenses, check the ownership rules, contribution requirements, tax considerations, and investment choices associated with each account.
Don't assume every brokerage offering an IRA or taxable account also supports these specialized arrangements.
Evaluate Cryptocurrency Separately
Cryptocurrency access is another major difference among investing platforms.
Some traditional brokerages don't offer direct cryptocurrency trading, while other platforms allow customers to purchase selected digital assets, sometimes including fractional amounts.
Crypto should be evaluated separately from conventional securities.
Investor protections may differ, cryptocurrency prices can be highly volatile, and digital assets may not receive the same protections that apply to eligible securities held through a brokerage.
Also check whether crypto can be held in the particular account type you're considering.
Understand Options and Margin Costs
Options trading may be advertised as commission-free while still carrying per-contract fees.
Small differences can become meaningful for investors regularly trading multiple contracts.
Margin requires even more caution. Borrowing money from a brokerage can increase your purchasing power, but it also magnifies potential losses. Interest is charged on borrowed funds, and adverse market movements can potentially result in forced sales or requirements to add assets.
Don't choose a brokerage's margin service based solely on how much you're allowed to borrow.
Check Fractional-Share Availability
Fractional shares can make portfolio construction easier when you're investing relatively small amounts.
Instead of purchasing one full share, you specify a dollar amount and receive the corresponding fraction.
This can help you distribute money among several investments without allowing high share prices to dictate your allocations.
Availability varies, however. A brokerage may support fractional trading for certain stocks and ETFs but not every security.
Separate Cash Features From Investing Features
Online brokerages increasingly combine investment accounts with cash-management services.
Depending on the platform, these may include interest on uninvested cash, checking or spending accounts, debit cards, automated transfers, or purchase round-ups.
These features can be convenient, but compare them independently from the brokerage's investing capabilities.
Interest rates can change, subscription requirements may apply, and deposit insurance depends on how eligible cash is held.
Understand Brokerage Protection
Brokerage protection is frequently misunderstood.
Applicable securities-investor protection generally addresses certain situations involving the failure of a brokerage and missing customer assets, subject to coverage rules and limits.
It doesn't reimburse you because a stock, ETF, option, or other investment loses value.
Certain assets offered through related services may also fall outside traditional brokerage protection, making it important to understand which legal entity actually holds each type of asset.
Choose Based on What You Plan to Invest In
Two brokerages can look nearly identical if you're comparing only commission-free stock trades. Their differences become much clearer once you examine the complete investment experience.
Consider the available securities, retirement and family accounts, managed-investment options, fractional shares, specialized trading fees, margin costs, cash features, research tools, and investor protections.
The most useful brokerage isn't necessarily the one offering the most features. It's one whose account structure and investment choices support the way you intend to manage your portfolio now while leaving enough flexibility for your needs to change.