An M1 Finance review needs to start with what makes the platform different. M1 combines self-directed portfolio construction with automation rather than operating exactly like a conventional brokerage or traditional robo-advisor.
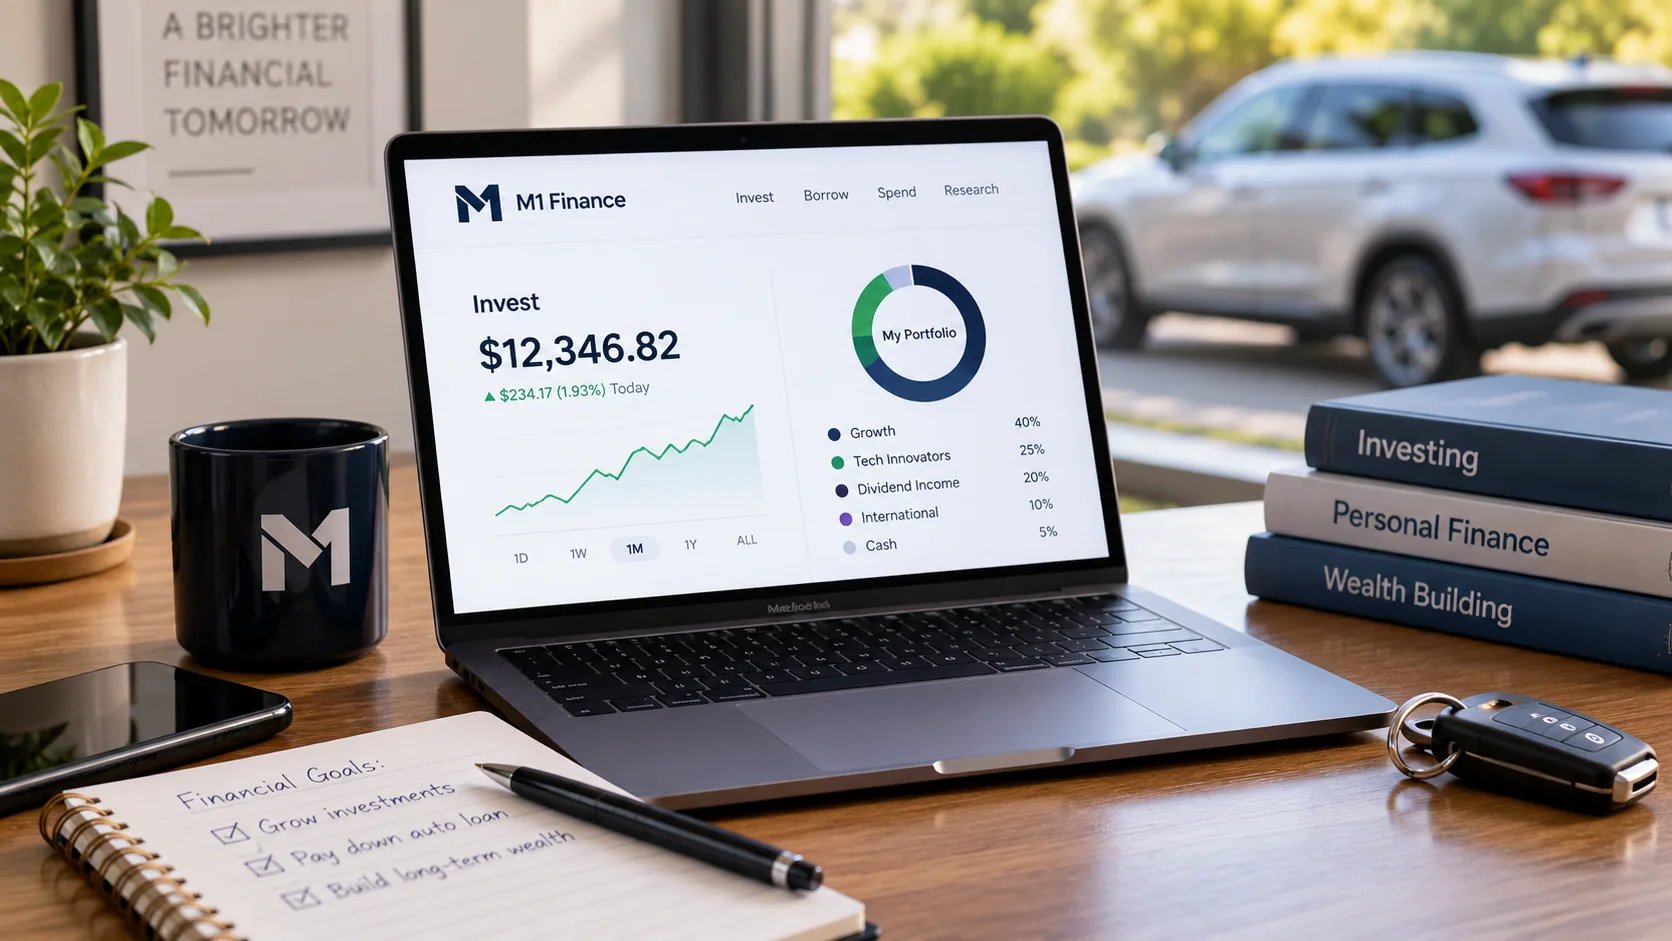
Its signature feature is the Pie system, which lets investors divide a portfolio into percentage-based allocations called Slices. M1 then offers tools that can direct new money toward those targets. Investors can access more than 6,000 U.S.-listed stocks and ETFs, while mutual funds and options aren't currently supported.
M1 may therefore make the most sense for investors who like deciding what they own but want automation to handle some of the repetitive portfolio management. Investors who prioritize intraday order control, options, mutual funds, or automated tax-loss harvesting may find the platform more restrictive.
M1 Finance at a Glance
Here are some of the main features prospective users should understand:
| Feature | Current M1 Offering |
|---|---|
| Stocks and ETFs | 6,000+ U.S.-listed stocks and ETFs |
| Online trading commission | Commission-free, although other fees may apply |
| Platform fee | $3 per month unless waiver requirements are met |
| Individual account minimum | $100 initial deposit |
| IRA minimum | $500 initial deposit |
| Trust minimum | $5,000 initial account value |
| Trading windows | 9:30 a.m. and 3:00 p.m. ET |
| High-Yield Cash Account | 3.10% APY |
| Margin eligibility | At least $2,000 in marginable securities |
| Options | Not supported |
| Mutual funds | Not supported |
| Tax-loss harvesting | Not offered |
M1's published information confirms the investment minimums, supported securities and trading windows. Its High-Yield Cash Account currently advertises a variable 3.10% APY, and M1 notes that rates may change.
How M1 Finance Pies Work
M1 Finance Pies are the central organizing system behind the investing experience.
Instead of viewing a portfolio only as a collection of individual positions, users create a Pie containing Slices. Each Slice represents an investment or another Pie and receives a target percentage.
For example, an investor could theoretically create a portfolio with target allocations such as 60% broad-market ETFs, 20% international ETFs and 20% selected stocks. Those percentages are choices made by the investor; M1 isn't guaranteeing that a particular allocation will produce better returns.
A portfolio can contain up to 100 Slices, and each Slice generally needs at least a 1% target allocation. M1 also offers Model Portfolios for investors who prefer a prebuilt starting point.
This approach makes M1 unusual. You retain substantial control over portfolio construction while gaining tools designed to automate how incoming money gets allocated.
Dynamic Rebalancing Versus Full Rebalancing
An important distinction is that M1 does not automatically perform a full portfolio rebalance without the investor's instruction.
Instead, Auto-Invest prioritizes Slices that are underweight relative to their targets when allocating new money. That can gradually move a portfolio closer to its chosen percentages without necessarily selling overweight holdings. A full rebalance is a separate action and can involve both purchases and sales.
That distinction can matter in taxable accounts because selling investments may create tax consequences.
How M1 Finance Investing Works
The appeal of M1 Finance investing is the combination of customization and automation.
Users can build their own portfolios from supported stocks and ETFs or use M1 Model Portfolios as a starting point. M1 supports more than 6,000 U.S.-listed stocks and ETFs from major exchanges. It also offers selected cryptocurrencies through separate Crypto Accounts.
However, M1 isn't designed to support every investment product. Its current documentation says mutual funds, options and over-the-counter securities aren't supported.
That makes M1 better aligned with investors building portfolios primarily from stocks and ETFs than someone looking for a brokerage with an especially broad menu of tradable securities.
How Auto-Invest Works
Automation is one of M1's more useful features for long-term portfolio management.
Auto-Invest is enabled by default. Investors choose a minimum amount of cash they want to leave in the investment account. Once available cash reaches at least $25 above that minimum, M1 can automatically place an investment order.
Rather than simply splitting the money equally, M1 looks at the portfolio's target allocations and prioritizes underweight Slices.
For example, if one ETF has fallen below its target percentage while another has risen above its target, incoming money may be directed more heavily toward the underweight investment.
Investors who don't want automatic purchases can switch Auto-Invest off.
M1 Finance Fees: What Does the Platform Cost?
Understanding M1 Finance fees is particularly important for investors with smaller balances.
M1 currently charges a $3 monthly platform fee for clients who don't meet its waiver requirements. The fee is automatically waived when an investor either has at least $10,000 in total qualifying M1 assets for at least one day during the 30-day billing cycle or maintains an active M1 Personal Loan.
IRA-only customers may instead face a $3 monthly IRA fee when they don't qualify for a waiver. M1 says a client won't be charged both the platform fee and IRA fee in the same month.
The dollar amount is fixed, so its relative impact depends on account size. At $3 per month, an investor who pays the fee for an entire year would spend $36.
That's equivalent to:
- 3.6% of a $1,000 balance
- 0.72% of a $5,000 balance
- 0.36% of a $10,000 balance
Those percentages simply illustrate the fee relative to hypothetical account balances; they don't account for investment gains, losses, deposits or withdrawals.
M1 also lists separate service and regulatory charges for certain activities, so investors should review the current fee schedule rather than assuming every transaction or service is free.
M1 Finance Brokerage Account Minimums
The initial deposit required for an M1 Finance brokerage account varies by account type.
M1 currently lists these minimum initial deposits:
- Individual, joint and custodial accounts: $100
- Traditional, Roth and SEP IRAs: $500
- Trust accounts: $5,000
- Crypto accounts: $100
After the initial funding requirement is satisfied, M1 says additional deposits can generally be $10 or more.
M1 supports individual and joint brokerage accounts, custodial accounts, traditional, Roth and SEP IRAs, trust accounts, High-Yield Cash Accounts and Crypto Accounts.
Trading Works Differently From a Conventional Brokerage
One of the biggest considerations in this M1 Finance review is trade execution.
M1 uses scheduled trading windows rather than giving investors the same intraday trading experience they might expect from a conventional brokerage.
The platform lists two trading windows:
- Morning: 9:30 a.m. ET
- Afternoon: 3:00 p.m. ET
Trades are generally queued for an available window rather than immediately executing when an investor presses the buy or sell button.
For an investor making regular long-term contributions, this structure might not be a major concern. It can be considerably less appealing to someone who wants tight control over execution timing or actively responds to intraday price movements.
The price displayed when an order is submitted therefore shouldn't be assumed to be its eventual execution price.
M1 Finance Cash Account
The M1 Finance cash account, formally called the High-Yield Cash Account, provides an interest-bearing place for eligible clients to hold cash.
As of M1's current published information, the account pays a variable 3.10% APY. M1 states that its High-Yield Cash Accounts can provide FDIC insurance eligibility of up to $4.75 million through its network of participating banks, subject to applicable program conditions and limits.
M1 also notes that cash held in its Individual, Joint, IRA, Trust and Custodial investment accounts doesn't earn interest simply by sitting there.
The distinction is important: investors who intentionally maintain significant cash should understand where that cash is held rather than assuming every uninvested balance receives the advertised APY.
Rates are variable, so the 3.10% APY can change.
M1 Finance Margin Loans
M1 Finance margin loans let eligible investors borrow against securities in their portfolios.
M1 says eligible Individual, Joint and Trust accounts need at least $2,000 in marginable securities to use the feature. Retirement and custodial accounts aren't eligible. Eligible borrowers may be able to borrow up to 50% of portfolio value.
M1 currently publishes a 5.65% margin rate while noting that rates may vary and can change. Interest accrues daily and is billed monthly.
Margin deserves considerably more caution than ordinary portfolio automation.
Borrowing against investments increases risk because the securities securing the loan can decline in value. Investors can face maintenance requirements and potentially be forced to sell securities. A relatively low borrowing rate doesn't remove those risks.
For that reason, the existence of margin shouldn't by itself be treated as a reason to choose M1.
What M1 Finance Does Well
M1's strongest feature is how its portfolio tools fit together.
Portfolio Customization
Investors decide which supported investments they want and how much of the portfolio each Slice should represent.
Automated Allocation
Auto-Invest can put available cash to work once it reaches the required threshold above the user's minimum cash setting. New investments are directed toward underweight Slices based on target allocations.
Fractional Portfolio Structure
Percentage-based Pies make it relatively straightforward to think about a portfolio in terms of allocation rather than simply the number of shares owned.
Multiple Account Types
M1 supports taxable brokerage accounts, several IRA types, custodial and trust accounts, among others.
These features can make the platform appealing to people who want more portfolio control than a conventional robo-advisor provides without manually managing every recurring investment.
Where M1 Finance Has Limitations
No brokerage fits every investing style, and M1 has several meaningful limitations.
Limited Trade Timing
Scheduled trading windows make the platform less suitable for investors who prioritize precise intraday execution.
No Options or Mutual Funds
M1 supports thousands of stocks and ETFs, but options and mutual funds aren't currently available.
No Automated Tax-Loss Harvesting
M1 explicitly states that it doesn't offer tax-loss harvesting. Instead, it uses a tax-minimization strategy when selecting tax lots for certain sales.
Those aren't the same thing. Investors specifically looking for automatic tax-loss harvesting should take this distinction into account.
Monthly Fee for Some Investors
The $3 monthly charge is small in absolute terms but can represent a more noticeable percentage of a small portfolio. Investors who don't meet the waiver conditions should include the fee when comparing M1 with competing brokerages.
Is M1 Finance Safe?
M1 Finance LLC is registered with the Securities and Exchange Commission as a broker-dealer and is a member of FINRA and the Securities Investor Protection Corporation (SIPC).
SIPC protection should not be confused with protection against investment losses. It addresses missing cash and securities when a SIPC-member brokerage fails, subject to applicable limits and rules; it doesn't reimburse investors simply because their stocks or ETFs decline in value.
Similarly, FDIC insurance associated with eligible swept cash applies under the conditions of M1's cash sweep program and participating banks. It doesn't insure investments such as stocks or ETFs.
Who Might Consider M1 Finance?
M1 may deserve consideration from investors who:
- Primarily invest in stocks and ETFs
- Prefer long-term portfolio strategies over frequent trading
- Want to define their own target allocations
- Like automated recurring investing
- Find the Pie interface intuitive
- Are comfortable with scheduled trading windows
It may be less suitable for investors who:
- Want options or mutual funds
- Trade frequently throughout the day
- Need precise control over order execution
- Specifically want automated tax-loss harvesting
- Don't want to pay a monthly platform fee and won't qualify for a waiver
The important question isn't simply whether M1 is a "good" platform. It's whether its particular approach matches how you intend to invest.
Is M1 Finance Worth Considering in 2026?
M1 stands out less for having the broadest investment selection and more for the way it combines investor-controlled portfolios with automated allocation.
The Pie system is particularly well suited to investors who think in terms of target percentages and want new contributions automatically directed toward underweight investments. Auto-Invest can reduce some repetitive portfolio work while leaving the underlying investment decisions with the account owner.
There are trade-offs. M1's scheduled trading windows limit execution flexibility, mutual funds and options aren't supported, automated tax-loss harvesting isn't available, and some investors will pay the $3 monthly platform fee.
For long-term stock and ETF investors who value portfolio customization and automation, those compromises may be reasonable. For active traders or investors who need a wider range of securities and trading tools, another brokerage may be a better match.
Ultimately, an M1 account should be evaluated around how you invest, not around any single feature, APY or margin rate. Fees and rates can change, so prospective customers should verify M1's current terms before opening or funding an account.