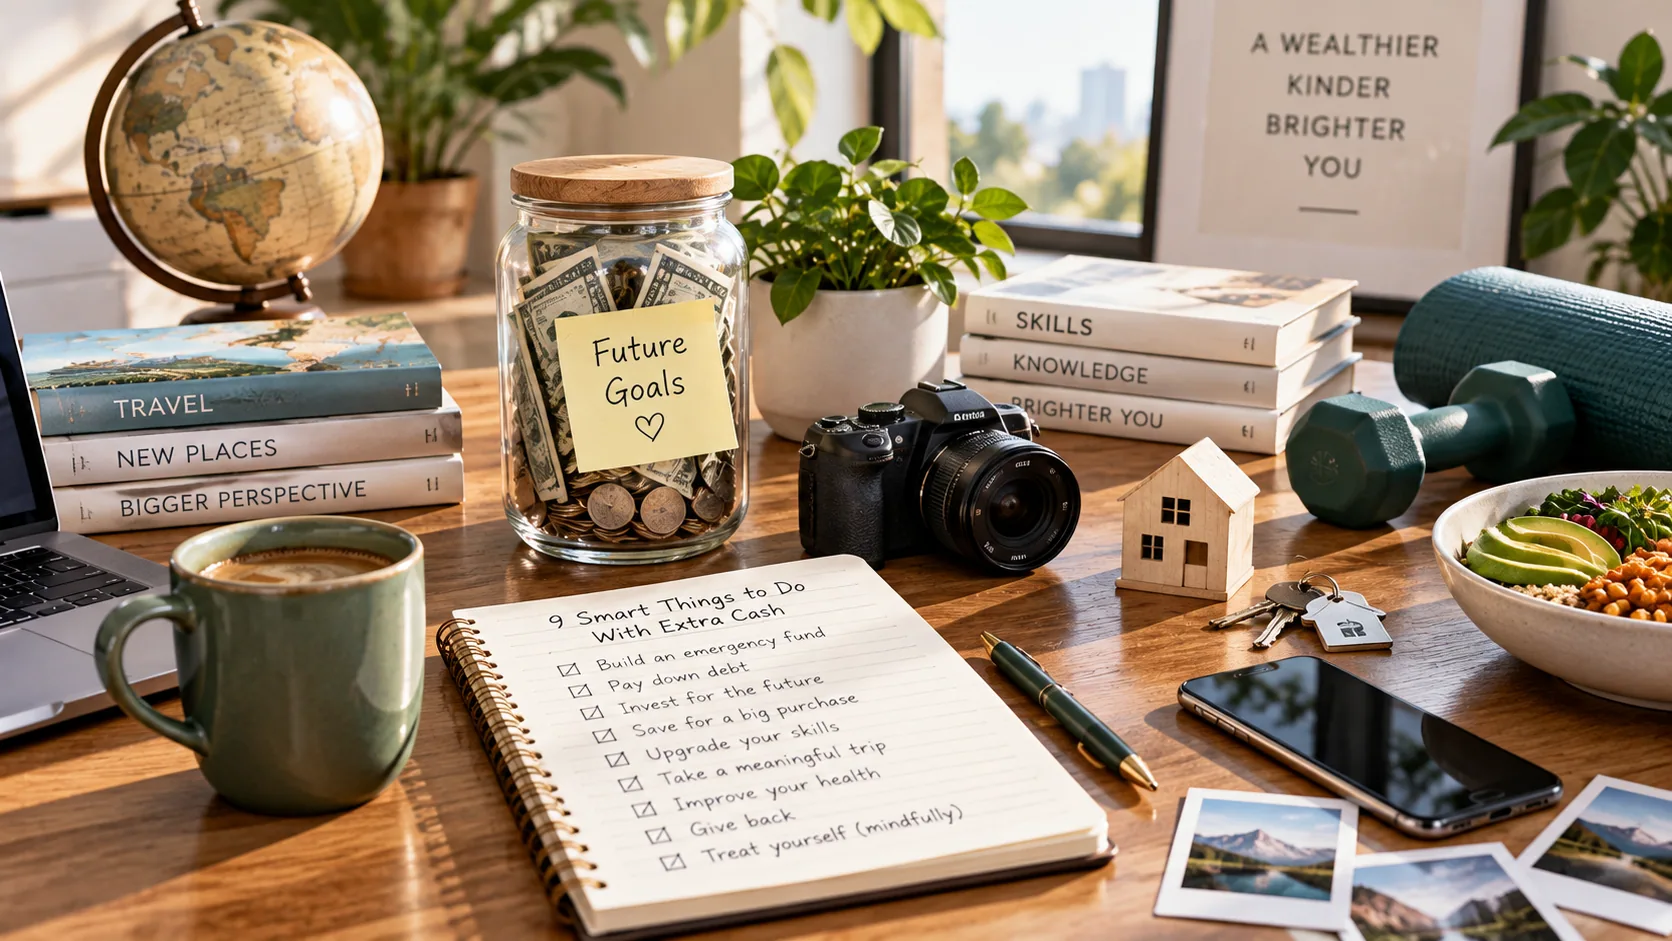
Figuring out what to do with extra cash can be surprisingly difficult. Leaving every spare dollar in your checking account may feel safe, yet that money could potentially serve a better purpose elsewhere. Depending on your finances, you might use it to strengthen your savings, reduce expensive debt, contribute toward retirement, or begin investing.
There is no single place where spare cash belongs. Money needed soon generally calls for a different approach from money you can leave untouched for years. Your debt, cash reserves, financial goals, risk tolerance, taxes, and access to employer benefits can all influence the decision.
Before moving the money, compare your options and decide what job you want those dollars to perform.
What to Do With Extra Cash: Start With Your Priorities
Before choosing a financial product, answer a few basic questions:
- Do you have enough cash available for unexpected expenses?
- Are you carrying high-interest debt?
- Will you need this money within the next few years?
- Does your employer provide a retirement contribution match?
- Are you comfortable with the possibility that invested money could decline?
- Are you saving toward a specific purchase?
- Do you already have investments?
These questions can help separate money that needs to remain accessible from money that may be available for longer-term goals.
Here's a quick comparison.
| Option | May Make Sense For | Main Advantage | Main Limitation |
|---|---|---|---|
| Savings account | Near-term needs | Easy access | Returns can vary |
| CD | Cash not needed until a known date | Fixed term and stated rate | Early withdrawal may carry a penalty |
| Treasury securities | Short- or intermediate-term goals | Backed by the U.S. government | Selling before maturity can affect value |
| High-interest debt repayment | Borrowers paying expensive interest | Reduces future interest charges | Money used for debt becomes less accessible |
| 401(k) | Retirement | Tax advantages and possible employer contributions | Withdrawal restrictions may apply |
| IRA | Retirement | Tax-advantaged investing | Eligibility and contribution rules apply |
| Brokerage account | Long-term investing outside retirement accounts | Flexible investment choices | No protection against investment losses |
| ETF or mutual fund | Diversified market exposure | Can hold many securities in one fund | Fees and market risk apply |
| Goal-specific savings | Planned expenses | Keeps money assigned to a purpose | May provide limited growth |
The right choice may involve several of these rather than one.
1. Strengthen Your Emergency Savings
An emergency fund provides money for expenses you did not plan for, such as a major car repair, urgent home expense, or period of lost income.
The appropriate amount depends on your circumstances. Someone with variable income or significant financial obligations may prefer a larger cash reserve than someone with predictable income and lower monthly expenses.
Accessibility matters here. Emergency money generally needs to be available without forcing you to sell investments during an unfavorable market.
An FDIC-insured deposit account can provide federal deposit insurance within applicable limits. The standard FDIC insurance amount is $250,000 per depositor, per insured bank, for each account ownership category.
Once you are comfortable with your cash reserve, you can assess other uses for additional money.
2. Move Short-Term Savings Where They Can Earn Interest
Cash intended for upcoming expenses may still have time to earn interest.
A high yield savings account can be worth comparing if your current bank pays a relatively low annual percentage yield. These accounts generally work similarly to standard savings accounts while potentially paying a higher rate.
When comparing accounts, check:
- Annual percentage yield
- Monthly maintenance fees
- Minimum balance requirements
- Minimum opening deposit
- Withdrawal and transfer options
- ATM access, if relevant
- Deposit insurance
- Requirements for earning the advertised rate
Rates can change, so a high APY today does not guarantee the same return later.
You should also check whether a financial institution is FDIC-insured rather than assuming coverage based on how an account is marketed.
3. Pay Down Expensive Debt
Extra cash may have considerable value when directed toward high-interest debt.
Suppose you have a credit card charging a high annual percentage rate. Paying down that balance reduces the amount subject to future interest charges. Unlike investment returns, the interest expense you avoid does not depend on stock-market performance.
Start by listing debts with their:
- Outstanding balances
- Interest rates
- Minimum payments
- Remaining repayment terms
- Prepayment penalties, if any
Prioritizing the highest-rate balance can reduce interest costs efficiently, although some people prefer eliminating smaller balances first for motivational reasons.
There is a trade-off. Cash used to repay debt is no longer sitting in your bank account. Keeping adequate cash reserves before making a large additional debt payment can reduce the chance that another unexpected expense sends you back to borrowing.
4. Capture an Available Employer Retirement Match
If your workplace retirement plan includes an employer match, review its terms before sending all spare money elsewhere.
Employer matching formulas vary. Your company might contribute based on how much you put into the plan, subject to the plan's rules. Vesting requirements can determine when employer contributions fully belong to you.
For 2026, the employee elective-deferral limit for 401(k), 403(b), and most governmental 457 plans is $24,500. The general catch-up limit for participants age 50 and older is $8,000, with separate rules applying in certain situations.
You do not necessarily need to contribute the maximum. Start by checking your employer's matching formula, vesting schedule, available investments, and plan fees.
5. Use an IRA for Retirement Savings
An individual retirement account can provide another tax-advantaged route for retirement money.
Traditional and Roth IRAs have different tax treatment and eligibility rules. Roth IRA eligibility, for example, depends partly on income.
For 2026, the combined annual contribution limit across traditional and Roth IRAs is generally $7,500, or $8,600 for someone age 50 or older, subject to taxable compensation and other applicable rules.
An IRA is an account rather than a specific investment. Depending on the provider, money inside an IRA might be invested in stocks, bonds, mutual funds, ETFs, and other eligible assets.
Compare providers based on investment choices, account charges, trading costs, research tools, customer service, and other features you expect to use.
6. Look at CDs for Money With a Defined Timeline
A certificate of deposit may make sense when you have money you will not need immediately but do not want exposed to stock-market risk.
CDs generally pay interest in exchange for leaving money deposited for an agreed period. Terms can range from months to several years.
Check these details before opening one:
- APY
- Term length
- Minimum deposit
- Early withdrawal penalty
- Renewal policy
- Deposit insurance
A CD can be inconvenient if you unexpectedly need the money before maturity. Some institutions provide no-penalty CDs, though their rates and terms may differ from standard CDs.
CD ladders are another possibility. Instead of placing all the money into one maturity date, you can divide it among CDs with different terms.
7. Review U.S. Treasury Securities
Treasury bills, notes, and bonds provide another place for money that you do not plan to put into stocks.
The appropriate security depends partly on your timeline. Treasury bills are short-term securities, while notes and bonds have longer maturities.
They carry the backing of the U.S. government when held to maturity, though their market prices can fluctuate if sold beforehand.
Treasury securities can be purchased directly through TreasuryDirect or through financial institutions and brokerage firms. Before buying, compare maturity, yield, liquidity needs, tax treatment, and any costs charged by the platform you use.
8. Invest for Longer-Term Goals
If your cash reserves are adequate, expensive debt is under control, and the money will not be needed soon, investing may become a reasonable option.
People researching how to invest extra money often start with a brokerage or retirement account and then choose investments inside it.
Common choices include:
- Stocks
- Bonds
- ETFs
- Mutual funds
For investing for beginners, diversified funds can provide a relatively straightforward way to hold numerous securities rather than selecting individual companies one at a time.
Investor.gov notes that mutual funds and ETFs can help investors diversify across companies or sectors, although narrowly focused funds may provide far less diversification.
Investments can decline in value. ETFs, for example, are not FDIC-insured, and investors can lose some or all of the money invested.
That makes your timeline important. Money for next month's rent has a very different job from money intended for retirement several decades away.
9. Save for a Specific Future Goal
Sometimes the best answer to what to do with extra money has nothing to do with maximizing returns.
You may have a known expense coming up, such as:
- A home down payment
- Education expenses
- A vehicle
- Home repairs
- Travel
- Starting a business
- Moving expenses
Keeping dedicated savings for a planned purchase may reduce the amount you eventually need to borrow.
Match the account to the timeline. Money needed relatively soon may be better suited to an accessible deposit account or another lower-risk option than a volatile investment.
Saving vs Investing: How Do You Decide?
The saving vs investing decision largely depends on when you expect to need the money and how much risk you can accept.
Saving generally emphasizes accessibility and preservation of principal. Investing accepts market risk in pursuit of potential returns.
| Question | Saving May Fit Better | Investing May Fit Better |
|---|---|---|
| When will you need the money? | Relatively soon | Several years away or longer |
| Can you tolerate a decline? | Little or no tolerance | Comfortable accepting market fluctuations |
| Is the goal an unexpected expense? | Generally yes | Generally no |
| Is the goal long-term growth? | Limited potential | Greater potential with greater risk |
| Do you need predictable access? | Often preferable | Depends on the investment and account |
| Is principal guaranteed? | Eligible insured deposits may be protected within limits | Generally no |
Investor.gov advises that investment choices should account for goals, timeframe, risk, fees, diversification, and liquidity.
You can use both approaches simultaneously. For example, you might maintain cash for emergencies and short-term expenses while investing separate money for retirement.
How to Compare Brokerage Accounts and Investment Funds
Once you decide to invest, choosing an account is only part of the decision.
Pay attention to what investing actually costs.
Account and Trading Fees
A brokerage may charge account, transfer, trading, advisory, or other fees depending on its pricing structure and the services you use.
Investor.gov recommends checking both transaction costs and ongoing account charges when evaluating an investment service.
Fund Expense Ratios
Mutual funds and ETFs generally have operating expenses that are deducted from fund assets.
Small differences can matter over long periods. The SEC notes that a higher-cost fund must perform better than a lower-cost fund to produce the same return for an investor.
Investment Selection
Check whether the brokerage provides the stocks, bonds, ETFs, mutual funds, and other investments you intend to use.
Having thousands of available investments may matter less than having suitable choices at reasonable costs.
Minimums
Some investment funds or managed services require minimum investments. ETFs can often be purchased for relatively small dollar amounts, although availability of fractional shares depends on the brokerage.
Research and Support
Some investors want screeners, research reports, calculators, educational materials, or access to professional advice. Others prefer a simple platform with automated recurring purchases.
Evaluate features according to what you will actually use rather than choosing a provider solely because it has the longest feature list.
Should You Invest All Your Extra Cash at Once?
Not necessarily.
First separate money needed for emergencies and near-term goals. Investing cash you may soon need could force you to sell during a market decline.
For money genuinely intended for long-term investing, your approach may depend on your risk tolerance, investment plan, and comfort with market fluctuations.
Some people invest available long-term money at once. Others prefer recurring investments on a schedule. Neither approach eliminates the possibility of losses.
What matters most is having a strategy you understand and can follow without putting necessary cash at risk.
Common Mistakes to Avoid With Extra Cash
Having spare money can create opportunities, yet a few decisions can undermine those benefits.
Leaving Large Balances in a Non-Interest-Bearing Account
Keeping enough in checking for bills can be practical. Cash substantially beyond your regular needs may have alternatives that pay interest while retaining suitable access.
Investing Money Needed Soon
Stock and bond prices fluctuate. If the money has a near-term purpose, taking market risk may create problems if prices fall shortly before you need to withdraw.
Ignoring High-Interest Debt
Investment returns are uncertain. Interest charged on existing debt follows the terms of the account. Compare the cost of your debt before deciding that investing should automatically come first.
Ignoring Fees
A platform advertised as commission-free can still have other costs. Funds can charge expense ratios, managed accounts can charge advisory fees, and some services have account or transfer charges.
Chasing Recent Performance
An investment that performed well recently may perform differently in the future. Investor.gov specifically warns that past performance does not predict future returns.
Choosing a Purpose for Your Extra Money
Deciding what to do with extra cash becomes easier once every dollar has a purpose.
Money for emergencies should generally remain accessible. Cash for a planned expense may fit a savings product with an appropriate timeline. Money intended for retirement or another distant goal may have time to accept investment risk in pursuit of potential growth.
From there, compare the actual products. Check APYs and withdrawal restrictions on deposit accounts. Review matching and vesting rules for workplace plans. Compare investment fees, fund expenses, diversification, and account features before opening a brokerage or retirement account.
Extra cash gives you choices. Assigning it according to your goals, timeline, debt, and tolerance for loss can help you choose among those options without taking risk simply for the sake of earning a potentially higher return.